Batteries, Generators, or Demand Response? What the Tariff Measures Decides
Each US market charges for transmission on a different measure, from one peak hour a year in PJM to every megawatt-hour in NYISO and CAISO. That measure decides whether demand response, generators or batteries can cut the bill, and in some markets none can.
For developers · For hyperscalers · For infra funds · For utilities · large-load · transmission · project-economics · procurement · cross-iso
Kris Narayanan · Tafel Power · September 13, 2026 · 12 min read
A transmission charge is a rate times a billing determinant. The determinant is the quantity being measured: your load in one particular hour, or in twelve, or every megawatt hour you drew all year. Rates get compared constantly. Determinants almost never do, and they vary far more.
Scope: the ISO comparison below covers wholesale transmission. The second table compares the analogous demand and delivery determinants in utility tariffs. Storage and on-site generation earn money in several other ways, including arbitrage, resource adequacy, ancillary services and backup reliability, and none of those are assessed here.
Four shapes, not eight tariffs
Every tariff below is one of four.
1. Coincident peak. PJM, ERCOT, MISO, SPP, ISO-NE. Your bill is set by how much you were drawing during a few specific intervals. Pull load down in those intervals and the bill falls.
2. Volumetric. NYISO, CAISO. Your bill follows total energy withdrawn. There is no peak to avoid. The only lever is using less.
3. Ratchet. Georgia Power, Alabama Power. A ratchet means the tariff remembers your highest reading and keeps billing you on it. A high demand reading can establish a billing floor that persists for as long as eleven months, and you cannot undo it once the meter prints it.
4. Fixed floor. Florida Power and Light, Umatilla Electric. The number was set by contract or by the equipment installed, so day-to-day operation barely touches it.
PJM is in the first group and behaves partly like the third.
What the seven markets measure
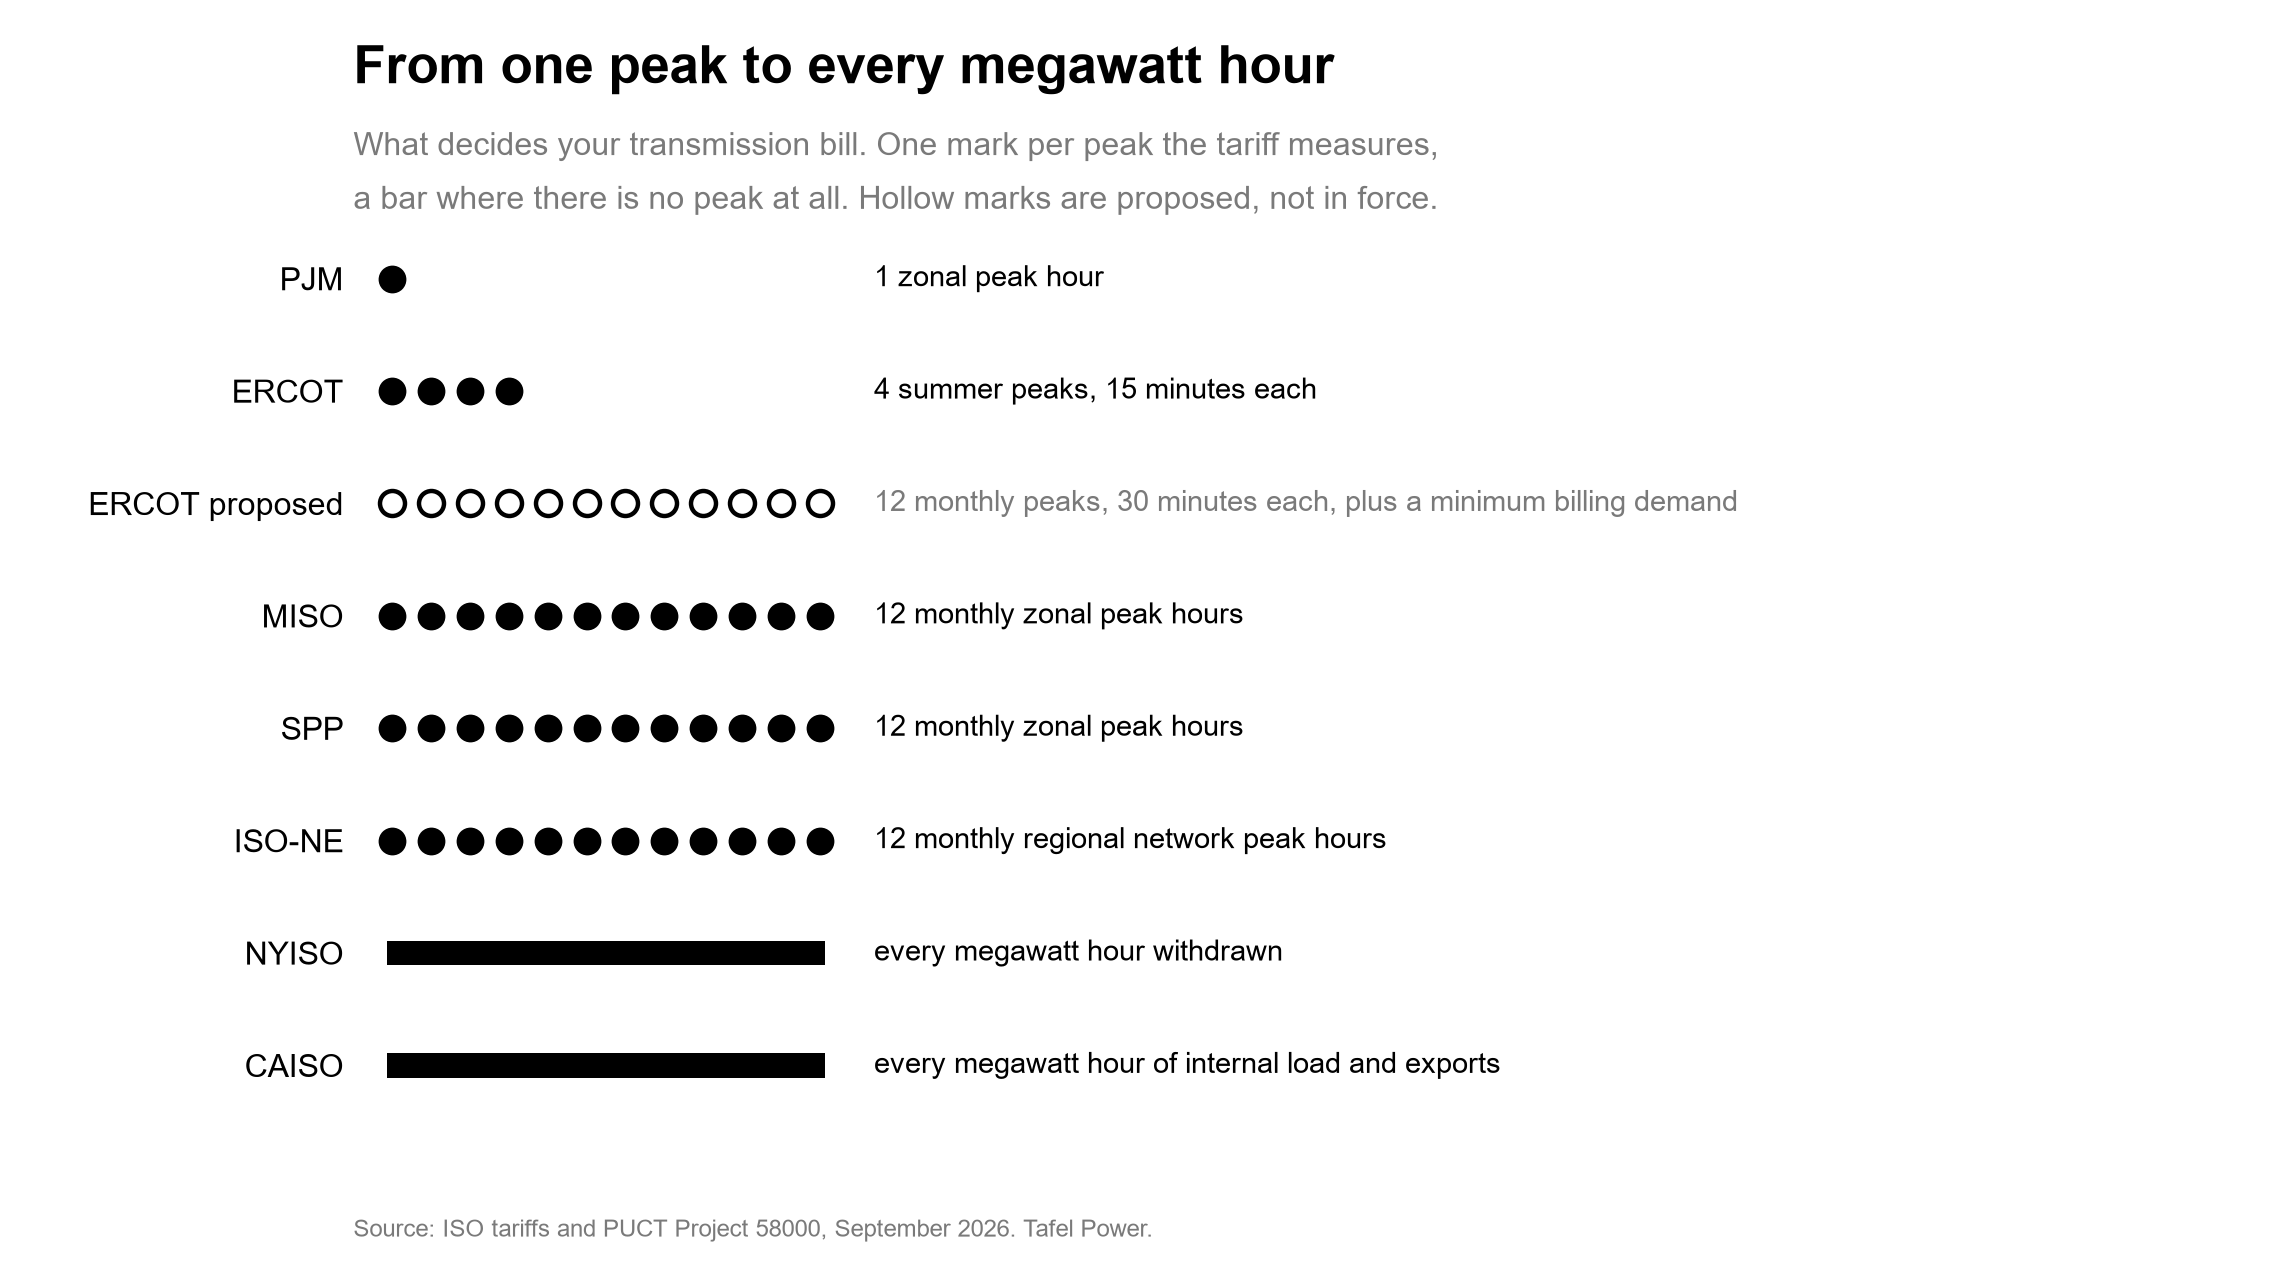
| market | core wholesale transmission determinant | transmission exposure |
|---|---|---|
| PJM | Network Service Peak Load, demand coincident with the zone's annual peak hour | 1 hour a year, per zone, then carried forward |
| ERCOT, in force | average of four 15-minute coincident peaks, June to September | 1 hour a year |
| ERCOT, proposed | twelve monthly 30-minute coincident peaks, plus a large load minimum billing demand | 6 hours a year, plus a floor |
| MISO | network load coincident with the monthly zonal peak | 12 hours a year |
| SPP | network load contribution at each zone's monthly peak | 12 hours a year |
| ISO-NE | monthly regional network load, the customer's load in the network's monthly peak hour | 12 hours a year |
| NYISO | transmission service charge on energy withdrawn, dollars per MWh | all consumption |
| CAISO | wholesale transmission access charge per MWh of internal load and exports | all consumption |
That column is transmission alone. Capacity is a separate charge with its own determinant, so a PJM load defending both is working against one NSPL hour plus five PLC hours, with possible overlap between them. PLC is the customer's average load across the five summer coincident peak hours. ERCOT is the clean contrast, with no capacity market at all. Capacity determinants for the other five are not loaded here.
The five that gets quoted for PJM is PLC, peak load contribution, which is the capacity determinant and a different charge. Transmission uses NSPL, and PJM heads its own publication "Metered Demand Coincident with Zonal Peak Load Hour." One hour, per zone, per year.
Which hour is not the same in every zone. Of the 21 zones PJM published for 2026, seven peaked in winter and fourteen in summer, six of the seven on a January morning.
| zone | peak | when |
|---|---|---|
| DOM | 24,678 MW | 23 January 2025, hour ending 8 |
| AEP | 23,710 MW | 22 January 2025, hour ending 8 |
| COMED | 20,714 MW | 23 June 2025, hour ending 18 |
| PSEG | 10,230 MW | 24 June 2025, hour ending 19 |
The two largest zones in PJM, Dominion and AEP, both set their peak on a January morning at hour ending 8. A load in either one that builds a summer-afternoon curtailment strategy is defending the wrong hour.
That one hour then bills you for the whole of the next calendar year, effective 1 January. Georgia Power gets to something similar by a different route, using an explicit rolling ratchet at 95 percent of your highest thirty-minute reading across eleven months, where PJM uses an annual coincident peak allocation. The mechanisms are not the same, but the customer is in the same position either way: one measurement they did not intend sets a bill they cannot operate their way out of. Persistence is not a quirk of southern utility tariffs.
CAISO assesses its wholesale transmission access charge on each megawatt hour of internal load and exports, at a system-wide rate identical for every participating transmission owner. A battery that shaves a California load's maximum demand by 100 MW changes the wholesale TAC by zero. The charge also falls on the Utility Distribution Company or Metered Subsystem Operator rather than on the end-use customer, and it establishes no end-use customer rate, so a California data centre never sees a TAC line on a bill. It meets the charge through its distribution utility, and that retail bill is a separate question with its own demand components.
The tariff layer adds floors the ISOs do not use
| utility | determinant | what it does to flexibility |
|---|---|---|
| Georgia Power, PLL | 30-minute demand, ratcheted 95% summer and 60% winter over eleven months | one bad reading persists for a year |
| Alabama Power, LPL | 15-minute maximum, floored at 90% of the June to September peak over eleven months | strong ratchet, plus a 1,200 kVA absolute floor |
| Florida Power and Light, LLCS | greater of 70% of contract demand or the highest billing demand in eleven months | a floor you cannot get under, and an upper limb you can defend |
| Umatilla Electric Cooperative, Schedule 6 | installed capacity, the nameplate of the transformers serving the member | curtailment cannot reduce this charge at all |
Those last two rows differ. FPL bills the greater of two things, so an asset can defend the upper limb: keep the eleven-month high from rising above 70 percent of contracted demand and the floor is all you pay. Nothing gets under the floor itself. Umatilla's delivery charge of $1.24 per kVA per month is billed on the transformers installed, so a load that curtails to zero for a year pays the same delivery charge as a load running flat out. That is the delivery charge only. Schedule 6 also passes wholesale power and transmission cost through to the member, and curtailment does reach that part.
LLCS-1 and LLCS-2 are approved and effective, having come in through FPL's 2025 rate settlement, approved by the Florida Public Service Commission on 22 January 2026 in Final Order PSC-2026-0022-S-EI. They are not settled. Florida Statutes section 366.043(8) requires every public utility to file a complying large load tariff for Commission approval no later than 1 October 2026. Whether LLCS already complies, is amended or is replaced is not established, so treat the 70 percent figure as correct today and dated.
Battery, generator, or demand response
Two of the four shapes split by degree at this question, so the table has six rows.
| determinant | instrument to test | decision logic |
|---|---|---|
| Few coincident peaks | DR, battery, or generator | DR if the process can stop. A battery if it cannot. A generator where duration or firm availability justifies the capital and running cost |
| Twelve monthly peaks | DR, battery, or generator | More events and year-round exposure raise the value of duration and firm availability |
| Volumetric | on-site generation, or genuinely forgone load | Must reduce grid withdrawals. Shifting load does not help, and grid charging can make the charge larger |
| Ratchet | generator, battery, or DR with a backstop | Stop the excursion before it prints. Reliability is the design criterion, not frequency |
| Contract demand floor | any of the three above the floor, none below it | Flexibility can stop actual demand from setting a higher billing demand. It cannot get under a binding contractual floor |
| Installed nameplate | none | Operational flexibility cannot change transformer nameplate |
Three things the table cannot hold.
In shape one the real question is not battery versus generator. It is how much interruption the process tolerates. ERCOT asks for four responses a year, June to September, historically between 16:00 and 17:45; PJM asks for one hour. Either way that is a small amount of interrupted operation. If the process can stop, demand response is the first instrument to test, because it needs little or no dedicated generation capital. If it cannot stop, the choice moves to batteries or generators, and duration, reliability, fuel economics and the number of expected events decide between them. In Texas this has been a curtailment practice far longer than a storage one.
Demand response splits in two under a volumetric charge. Shifting load does nothing: in CAISO the rate is flat per megawatt hour, and in the NYISO rates loaded here the on-peak and off-peak figures are identical. Genuinely forgone consumption does work, because the charge follows the meter total. So generators displace, forgone-consumption demand response reduces, and shifted demand response and grid-charged batteries do nothing or make it worse.
Demand response is the riskiest instrument under a ratchet. Against a coincident peak, a missed event costs you that interval's contribution for one year. Against a ratchet it is asymmetric: one failed curtailment prints the reading that sets the next eleven bills. Demand response alone is the wrong answer in Georgia and Alabama unless something sits behind it, an automated hard limit or firm on-site capacity. A firm generator can be that backstop itself, which is why it competes here better than its utilisation suggests. The shape sets the cost of the instrument failing, not just its value.
Two numbers worth pinning
The ERCOT number, and three things attached to it. A Charles River Associates report in ERCOT Board materials for April 2026 puts the 2025 rate recovering the ERCOT system annual transmission revenue requirement at $68.55 per kW-year. So a megawatt of average 4CP demand carried about $68,550 a year.
Average is the word doing the work, and it makes $68,550 a ceiling rather than a wage. The determinant is the mean of four intervals, so a megawatt taken off in all four is worth $68,550 and a megawatt taken off in one is worth a quarter of that.
You also cannot aim at the four. Protocol 9.17.1 publishes the determinants by 1 December, after the summer has finished, so a load chases them on a forecast. The same report notes that curtailments are much greater in anticipated 4CP hours than in other hours, which is the tell: to catch four intervals you curtail on considerably more than four afternoons, and the cost of those extra curtailments is the real price of the saving. The same report scopes the direct exposure to transmission-voltage customers and non-opt-in entities; every other load meets it through its Distribution Service Provider's cost recovery factor under 16 TAC 25.193, which is a separate tariff. And it is a consultant figure presented to the Board rather than an ERCOT tariff publication.
Our own build from filed tariffs reaches $32.719 per kW-year across two verified providers, which is a floor rather than the rate, and at 48 percent of that total it is about what a two-provider subset of roughly 130 should look like.
Why grid charging can backfire. A battery draws power to fill, then gives back less than it took, and a volumetric charge is assessed on what the meter records. Whether that bites depends on which meter the charging crosses: a battery filled by on-site solar does not behave like one filled from the grid. A California battery is normally built for arbitrage, resource adequacy and ancillary services, and this says nothing about any of those. It says the wholesale transmission access charge is not a line item storage can attack, so keep it out of that column.
What Texas is proposing
A proposed rule under PUCT Project No. 58000 was filed with the Secretary of State on 9 July 2026 and published in the 24 July Texas Register, as TRD-202602812 amending 16 TAC 25.192 and 25.193 and TRD-202602813 creating a new section 25.252. Comments closed 11 August and the earliest possible adoption date, 23 August, has passed. The rule remains pending, with a statutory deadline of 31 December 2026.
Four summer peaks become twelve monthly ones, which triples the surface to defend. And a large load customer would be billed on the greater of contracted peak demand, the past year's highest non-coincident peak, or its 12CP, for no less than twenty years. Where contracted peak demand is the limb that binds, curtailment cannot get underneath it. Texas would be adding a shape four floor to the market that currently pays the most for shape one behaviour.
No adopted rule text exists.
The decision
The question is not whether flexibility is worth something. It is which kind of flexibility can reach the number your bill is built on.
Against a few coincident peaks, start with demand response if the process can stop. If it cannot, batteries and generators compete on duration, reliability and economics. As the number of intervals rises, a generator gets more competitive, because availability and duration start to count for more than speed. Against a volumetric charge the asset has to cut grid withdrawals, which favours on-site generation over a grid-charged battery. Against a ratchet all three can work, but the excursion has to be stopped before it prints. Demand response needs a reliable backstop behind it; a battery or a firm generator can be that backstop itself. Where a contracted demand floor sets the number, any of the three can still stop actual demand from setting a higher number above that floor, but none of them gets underneath the floor itself, and the lever there is the contract. Where the number follows installed transformer capacity, operations have nothing to attack at all.
So the order is: find out what your tariff measures, define the operating problem that creates, then choose the instrument. Technology is the third question, not the first. Starting with the asset before you know what is being measured is how a plausible business case ends up solving the wrong problem.
Sources: 16 TAC 25.192 and 25.193 and ERCOT Nodal Protocol 9.17.1; the 2025 ERCOT system transmission rate from a Charles River Associates report in ERCOT Board materials for 20 to 21 April 2026, item 11.1 page 13; PUCT Project No. 58000 proposed rule, TRD-202602812 and TRD-202602813, filed with the Office of the Secretary of State 9 July 2026 and published in the 24 July 2026 Texas Register, comments closed 11 August 2026, earliest possible adoption 23 August 2026, adoption pending; PJM Network Service Peak Loads for 2026, which supplies every zonal peak figure and date quoted here, with PJM OATT Attachment M-2 for the ComEd zone read as the worked example of how a zone separates NSPL from PLC; MISO OATT Schedule 9 effective 1 June 2026; SPP OATT Sections 34.1, 34.4, 34.5 and Schedule 11, Docket ER26-1850-000 effective 1 April 2026; ISO-NE OATT Schedule 9 regional network service; NYISO OATT section 14.1 transmission service charge; CAISO transmission access charge, high voltage access charge rates effective 1 June 2026; Georgia Power PLL, Alabama Power LPL, Florida Power and Light tariff section 8 sheets 8.950 to 8.955 effective 1 January 2026 and approved in Florida Public Service Commission Final Order PSC-2026-0022-S-EI of 22 January 2026, Umatilla Electric Cooperative Schedule 6 effective 1 October 2025. Two ERCOT figures appear here and they are not the same quantity. The $68.55 per kW-year system transmission rate is the Charles River Associates figure carried in ERCOT Board materials, not an ERCOT tariff publication. The $32,719 per MW-year figure is this project's own build across two verified provider tariffs out of roughly 130, a floor rather than a statewide total, and it is shown only to size the gap between the two. The wholesale charge reaches a large load through its Distribution Service Provider's cost recovery factor under 16 TAC 25.193. Analysis: Tafel Power.
Questions, corrections or disagreement on any of this are welcome: kris@tafelpower.com
More from Insights
September 11, 2026
A Texas Power Plan Can Cost 9.8 Cents. Or 22.2.
Of 1,053 Texas residential electricity plans, 57 are cheaper per kWh at exactly 1,000 kWh a month than at 500 or 2,000. They list a median 9.8 cents at 1,000 kWh and 22.2 cents at 500, so a household's own usage decides which is cheapest.
September 3, 2026
The Utility Publishes the Process. Not the Price of Finding Out.
In Wisconsin the public record sets a 100 MW load's tariff, 15-year term and security. It does not say what the next utility study costs, and the first answer back is a sentence, not a megawatt figure or a date.