Insights
Original analysis for power infrastructure transactions, large-load strategy and investment decisions across US power markets. Each analysis ends in a decision you can act on, states what would prove it wrong, and shows its working.
49 analyses · Jan 2026 to present
Latest
October 28, 2026
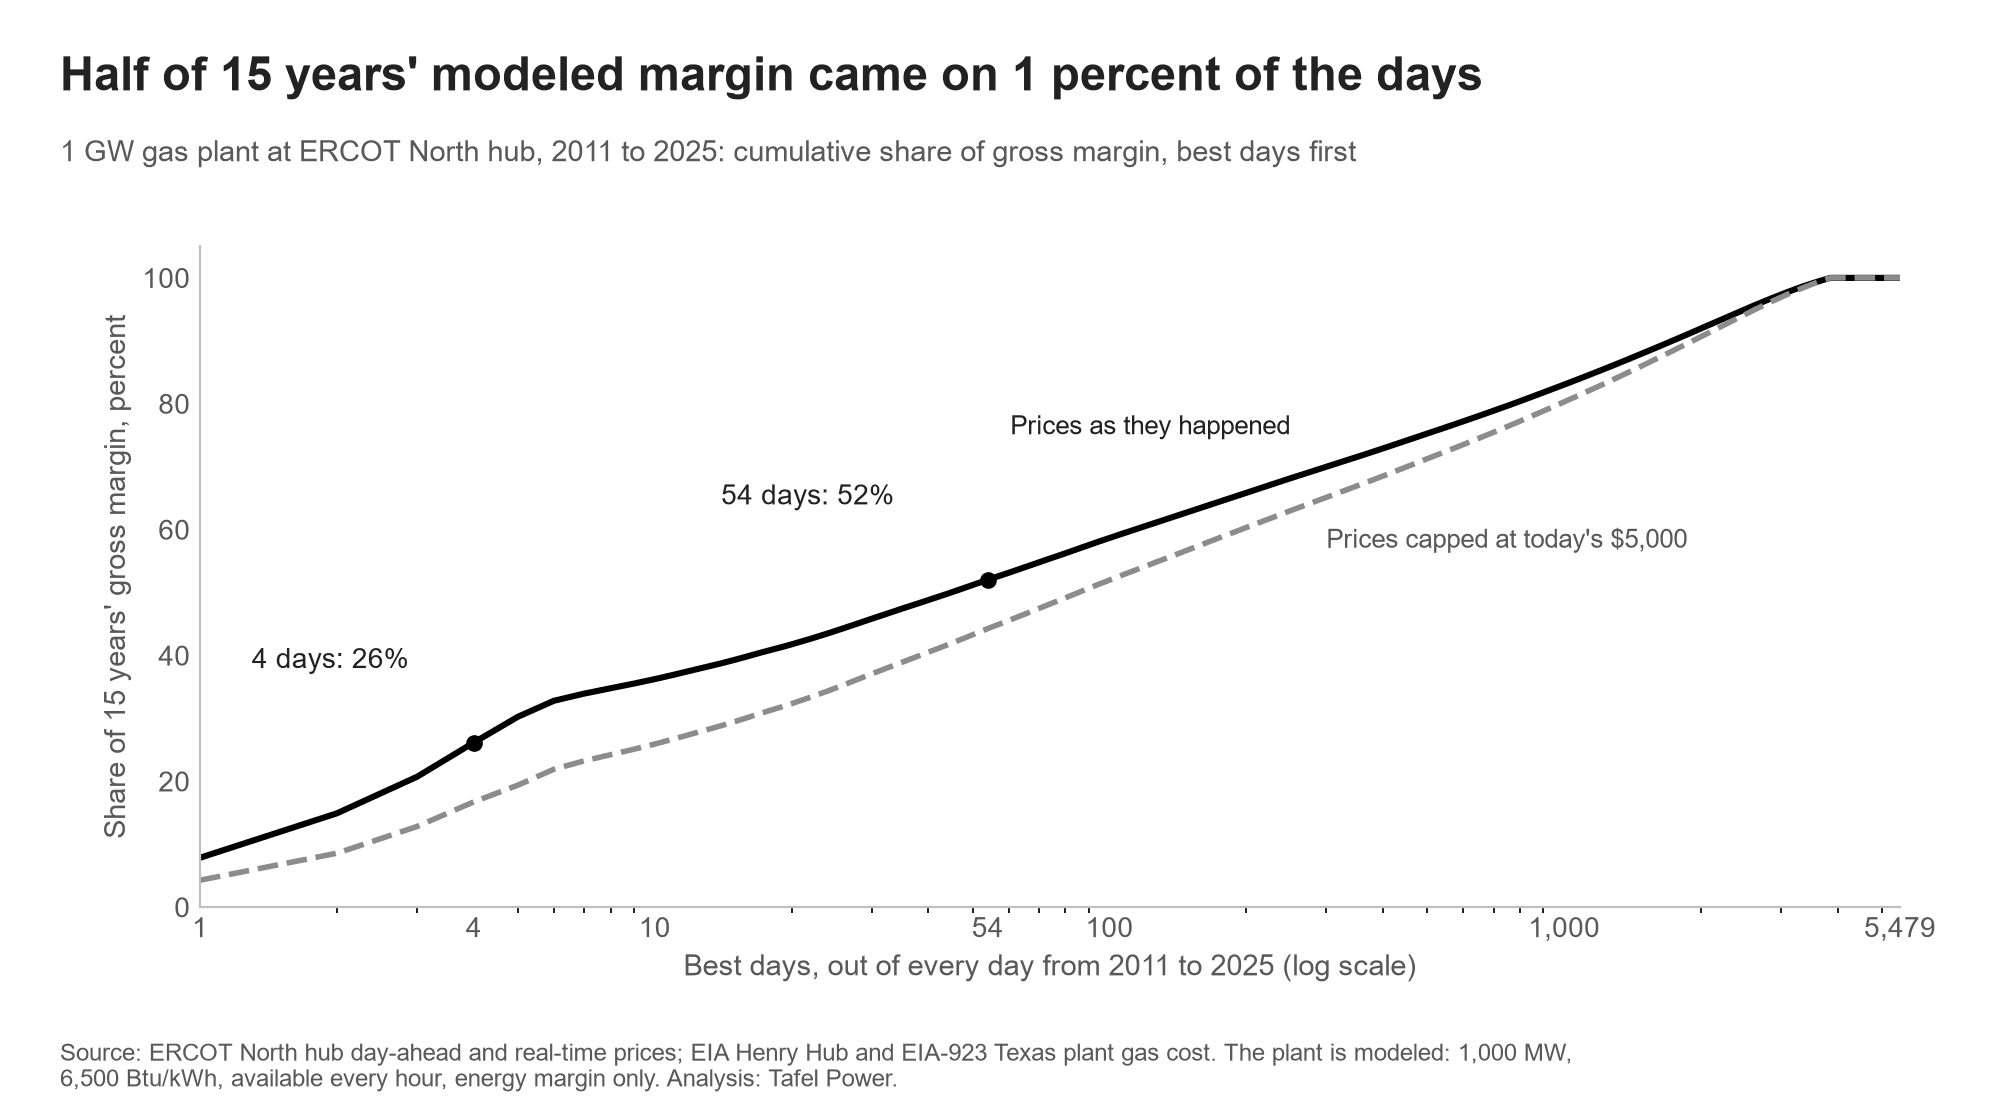
Half a Gas Plant's Earnings Came on 1 Percent of Its Days
Fifteen years of Texas power prices show that the days that create most of a gas plant's value are the days it is hardest to deliver.
Start here
Five analyses that set out how we think about large load power.
- Sep 2026How a Data Center Gas Plant Gets Paid
A gas plant built for a data center outlasts its contract by decades. What the money needs sets most of the price: a developer on a 10-year contract needs about 20 percent of build cost back a year, a long-term investor about 8 percent.
How a data center gas plant gets paid, part 1
- Sep 2026How a Utility Gets Paid
Across 19 US utilities, allowed earnings sit between 3.9 and 5.5 cents per dollar of rate base, while rate base spreads about 19 times even without the two smallest. The size of the rate base, not the return, decides who earns most.
- Aug 2026Fifty Percent of What?
Large power contracts set a minimum bill owed even if the load never arrives. On one 60 MW contract where only 30 MW shows up, it runs from 15 MW on a Texas campus to 51 MW in Virginia, because each measures against something different.
- Sep 2026The Utility Publishes the Process. Not the Price of Finding Out.
In Wisconsin the public record sets a 100 MW load's tariff, 15-year term and security. It does not say what the next utility study costs, and the first answer back is a sentence, not a megawatt figure or a date.
- Sep 2026The Hidden Clocks of Power
A power company that misses plan in year one in a new market could have any of at least eleven problems, each needing a different fix, and leaders have to choose before the data can tell them which.
Reference
Tables of filed terms and plants, updated as the record changes.
- Aug 2026Large-Load Power Contracts: The Record
Four large-load power structures, AEP Ohio, Dominion Virginia, Entergy Louisiana and a private Texas campus, compared on term, minimum bill, fuel, exit and collateral, as their tariffs, orders and filings state them.
- Sep 2026Data Center Gas Plants: The Record
Thirty-one gas plants that public filings tie to data center load, in five groups, with what each filing states about contract term, who holds the fuel price and any dollar backstop. Read from commission orders, SEC filings, permits and company releases.
Getting power
What decides whether a site gets power, from whom, and how long it takes.
- Sep 2026Batteries, Generators, or Demand Response? What the Tariff Measures Decides
Each US market charges for transmission on a different measure, from one peak hour a year in PJM to every megawatt-hour in NYISO and CAISO. That measure decides whether demand response, generators or batteries can cut the bill, and in some markets none can.
- Sep 2026The Utility Publishes the Process. Not the Price of Finding Out.
In Wisconsin the public record sets a 100 MW load's tariff, 15-year term and security. It does not say what the next utility study costs, and the first answer back is a sentence, not a megawatt figure or a date.
- Jul 2026Can Entergy Serve the Next Gigawatt?
Entergy has about 11 GW of new gas planned and filed for 5.2 GW more in March 2026, with the added cost assigned to the customers who trigger it. Few utilities can commit firm power at this scale, typically from around 2028.
MISO
- Jul 2026If You Can't Get a Turbine Until 2029, What Powers the Load?
A new heavy-duty gas turbine ordered today may not arrive until about 2029. Until then, firm power comes fastest from flexing load onto existing grid headroom, buying from the existing fleet and uprating plants, then fuel cells and engines.
- Jul 2026What Actually Powers a 24/7 Data Center?
The US interconnection queue holds about 2,000 GW, 85 percent of it solar, wind and storage. A round-the-clock data center needs firm capacity, the scarce part of that queue, and firm supply sets both its time to power and its price.
- Jul 2026Batch Zero's Interim Framework and the $50,000 per MW Default
Texas approved Batch Zero in June 2026, an interim path for large loads into ERCOT studies before the full rule is written. Where upgrade costs are not yet known, security defaults to $50,000 per MW, or $50 million for a 1,000 MW load.
ERCOT
- Jul 2026When Faster Power Stops Being Expensive
The best way to energize early is not fixed. It moves with what your load earns, and on the illustrative case it changes twice: once at about $49 per MWh and again at about $114.
Contracts & commercial terms
The contracts, deposits and minimum bills a large load signs, and who carries what.
- Sep 2026How a Utility Gets Paid
Across 19 US utilities, allowed earnings sit between 3.9 and 5.5 cents per dollar of rate base, while rate base spreads about 19 times even without the two smallest. The size of the rate base, not the return, decides who earns most.
- Aug 2026Who Holds the Fuel Risk?
Gas moved by $39 to $59 a megawatt-hour over three years. Where that lands is a drafting choice, not a market fact.
- Aug 2026Fifty Percent of What?
Large power contracts set a minimum bill owed even if the load never arrives. On one 60 MW contract where only 30 MW shows up, it runs from 15 MW on a Texas campus to 51 MW in Virginia, because each measures against something different.
- Jul 2026Everyone Saw Mozal Coming. It Closed Anyway.
Mozal's smelter stopped making aluminum in March 2026 when its 950 MW power contract ended, after six years of trying to replace the supply and a $372 million write-off. The end date was known for years. Replacement power was not available.
- Jul 2026The Reciprocal Commitment Ladder: How Scarcity Determines Who Commits First
Large-load deals stall because the developer needs a signed buyer and the buyer needs a built plant. Tying each step of the buyer's commitment to a step of the developer's spending breaks the deadlock, with the side that has fewer alternatives committing earlier.
- Jul 2026The Data Center Is Not the Problem. The Deal Is.
About $9.3 billion of PJM's $14.7 billion 2025/26 capacity cost traces to data centers and is spread across 13 states and Washington DC, while host counties such as Loudoun keep the tax revenue. Who pays beyond the substation is the contested question.
- Mar 2026The Large-Load Financial Security Just Got Cut in Half
In March 2026 Texas proposed halving the upfront security for large power users, from $100,000 to $50,000 per megawatt, and June's Batch Zero framework uses $50,000 as its default. A 500 MW data center would post $25 million rather than $50 million.
ERCOT
Supply & equipment
What it takes to build and pay for firm supply, and where the equipment bottleneck sits.
- Sep 2026How a Data Center Gas Plant Gets Paid
A gas plant built for a data center outlasts its contract by decades. What the money needs sets most of the price: a developer on a 10-year contract needs about 20 percent of build cost back a year, a long-term investor about 8 percent.
How a data center gas plant gets paid, part 1
- Sep 2026What 15 Percent Takes on a Data Center Gas Plant
A gas plant built off-grid for one data center recovers about 20 percent of its cost a year on a 10-year contract. On the grid it still needs about 13 percent, while PJM and ERCOT markets pay about 1 to 5.5 percent at recent prices.
How a data center gas plant gets paid, part 2
- Aug 2026The Data Center Buildout Has a Toilet Paper Problem
At the end of the second quarter of 2026, 63 GW of GE Vernova's 116 GW turbine backlog was reserved production slots and only 53 GW was signed orders. Reservations show how scarce turbines are; signed orders are the better guide to durable demand.
- Aug 2026Gas Turbines Are Scarce. The Turbine Maker Reports a Thinner Margin.
GE Vernova, maker of the scarcest product in the data center power chain, reports an 18.8 percent margin on an EBITDA basis, below Eaton's 27.5 percent on an operating basis. Four parts of the chain report no separate return at all.
- Apr 2026The Turbine, Not the Interconnection Queue, Now Gates 2028 Gas
GE Vernova's turbine slot reservations rose from 43 GW to 56 GW in the first quarter of 2026, with new orders expected to price 10 to 20 percent higher. For 2027 and 2028 gas, a secured turbine now matters as much as an interconnection agreement.
New generation pipeline
Which queued plants are real, market by market, and where firm supply will come from.
- Jul 2026The ERCOT Queue Cannot Distinguish Captive Gas from Speculation
Project Kilby shows in ERCOT's queue as about 2.4 GW of unsigned gas, yet Chevron reports a 20-year agreement to supply Microsoft with about 2.67 GW from it. Queue status misses plants built for one customer, so they need their own diligence test.
ERCOT · The ERCOT gas queue, part 8
- Jul 2026How Much of ERCOT's 69.7 GW Gas Queue Is Credible?
Weight ERCOT's 69.7 GW gas queue by how often projects actually get built, about 60 percent for signed projects and 15 percent for unsigned, and it shrinks to about 17 GW.
ERCOT · The ERCOT gas queue, part 7
- Jul 2026The Second-Largest Signed, Near-Term Gas Queue Is in the Plains
SPP holds about 2.0 GW of signed, near-term merchant gas, mostly in Oklahoma and the Texas Panhandle. That is second only to ERCOT and more than PJM and MISO combined.
SPP · Signed, near-term gas across US markets, part 5
- Jul 2026ERCOT's Signed, Near-Term Merchant Gas Is a Fifteen-Counterparty Market
ERCOT's 8.8 GW of signed, near-term merchant gas sits with about fifteen companies, and the top five parent developers hold about 80 percent. With so few sellers, relationships and timing shape price more than competition does.
ERCOT · The ERCOT gas queue, part 6
- Jul 2026ERCOT's Signed, Near-Term Gas Is Concentrated in West Texas
Sixty percent of ERCOT's 8.8 GW of signed, near-term merchant gas is in West Texas. In the Dallas-Fort Worth zone, where much data center load wants to land, only 0.02 GW of 4.8 GW of queued near-term gas has a signed interconnection agreement.
ERCOT · The ERCOT gas queue, part 5
- Jul 2026Only 8.8 GW of ERCOT's Gas Queue Is Signed and Near-Term This Cycle
ERCOT's queue holds 69.7 GW of gas, but only 8.8 GW is merchant, holds a signed interconnection agreement and targets service in 2026 to 2028. That smaller set is what a buyer can actually contract this cycle.
ERCOT · The ERCOT gas queue, part 4
- Jul 2026Which ERCOT Queue Capacity Has a Signed Interconnection Agreement?
June 2026 snapshot. 434 GW in queue. 134 GW with signed interconnection agreements. Breakdown by technology.
ERCOT · The ERCOT gas queue, part 3
- Jun 2026West Virginia Leads PJM in Queued Gas. Most of It Is One Project.
West Virginia leads PJM with about 2.8 GW of queued gas, but 2.1 GW is one unsigned project and only about 0.6 GW is signed, near-term gas still to be built. With little existing gas generation, large loads there will likely need their own supply.
PJM · Signed, near-term gas across US markets, part 4
- Jun 2026PJM's Largest Data Center Market Is Relying on the Existing Fleet, Not New Gas
Northern Virginia leads PJM in forecast data center growth, about 6.7 GW to 2030, while all of PJM has only about 0.7 GW of signed, near-term gas still to be built. Firm power there comes from the existing fleet and the capacity market.
PJM · Signed, near-term gas across US markets, part 3
- May 2026In MISO, the Firm Gas Is in the Utility Plan, Not the Queue
MISO's queue shows only about 0.4 GW of signed, near-term merchant gas, yet Louisiana is building more new gas than any state, about 6.8 GW. In MISO, firm power comes through regulated utilities such as Entergy rather than the merchant queue.
MISO · Signed, near-term gas across US markets, part 2
- Apr 2026Ohio's Gas Queue Looks Empty Because Ohio Already Built Its Gas
Ohio's queue holds about 0.9 GW of signed gas, essentially one project, because the state already built about 6.4 GW during the Utica boom. Its strength for data centers is that existing fleet and nearby low-cost gas.
PJM · Signed, near-term gas across US markets, part 1
- Feb 2026The ERCOT Queue Has Fewer, Bigger Projects
The ERCOT queue fell below 2,000 projects in late 2025 while total capacity rose, so the average project grew from about 204 MW to 224 MW. Size alone says nothing about whether a project is financed.
ERCOT · The ERCOT gas queue, part 2
- Jan 2026Gas, Not Renewables, Is Driving ERCOT's Queue Growth
The ERCOT queue added about 21 GW in the second half of 2025, and about 18 GW of it was gas. Batteries and solar were flat.
ERCOT · The ERCOT gas queue, part 1
Returns & value
What power assets earn, and what they are worth.
- Oct 2026Where Does the Money From a Data Center Power Plant Go?
We modeled a 1,000 MW gas plant built to power a data center. Lenders and investors collect about seven times what the companies that build it earn, for putting up the money.
- Sep 2026The Demolition Is Priced. The Carbon Is a Study.
In one campus gas deal, Meta guarantees 20 years of minimum payments, the plant's value if it leaves early and the cost of demolition. The same contract's carbon terms commit to commercially reasonable efforts and one funded study.
- Jul 2026ERCOT Fleet Revenue Rose 8 Percent. Revenue per Megawatt Fell 37 Percent.
Installed ERCOT storage passed 17,000 MW in 2025, so fleet revenue rose 8 percent while revenue per megawatt fell 37 percent. What still earns is an asset's own advantage, and each advantage wears off over time.
ERCOT
- Jul 2026Clean Power Earns Nothing Where It Is Used Most
Europe's border carbon charge ignores the carbon in the electricity used to make aluminum, steel and hydrogen, so clean power earns nothing against it today. The exemption follows an EU subsidy and can end when that subsidy changes.
- Jul 2026Cheapest Energy Isn't Cheapest Power
An illustrative benchmark of what a 500 MW load at a 95 percent load factor pays for delivered power across the seven organized markets. Wholesale prices cluster between 30 and 55 dollars per MWh. Delivered, the displayed totals run from about 36 to about 87.
- Jun 2026LCOE Is Not a Deal Price
Cost curves rank solar and wind as the cheapest power at the plant gate. A data center buys a firm megawatt at a site on a date, and once capacity credit, interconnection and equipment lead times are counted, the ranking can change.
- Apr 2026What a Legacy Biomass Plant Is Actually Worth
A legacy biomass plant's grid connection, switchyard, permits and site near transmission can be worth more than its thin power margins, though using that connection to serve a data center still needs its own study.
Markets & policy
How market design and regulation change the next decision.
- Oct 2026Half a Gas Plant's Earnings Came on 1 Percent of Its Days
Fifteen years of Texas power prices show that the days that create most of a gas plant's value are the days it is hardest to deliver.
ERCOT
- Oct 2026The AI Campus Could Leave America. So Far It Has Not.
Every US site now has two gates: whether the grid can serve it, and whether the local utility's rates make the data center pay its own way.
- Oct 2026The Plant That Outlives the Bridge
A data center that pays enough during the bridge years can repay its gas plant before the grid arrives. Then the later years can become largely upside. If it does not, they are a bill. The disclosed contracts rarely say who gets which.
- Sep 2026A Texas Power Plan Can Cost 9.8 Cents. Or 22.2.
Of 1,053 Texas residential electricity plans, 57 are cheaper per kWh at exactly 1,000 kWh a month than at 500 or 2,000. They list a median 9.8 cents at 1,000 kWh and 22.2 cents at 500, so a household's own usage decides which is cheapest.
ERCOT
- Aug 2026Google, Microsoft, Amazon, Meta and Oracle Face the Same Carbon Problem. They Chose Five Different Answers.
Five big tech companies bought very different carbon instruments, costing from about $1 to $148 per megawatt-hour covered, which at their scale is billions a year. What each bought, and who pays if the rules change, matters more than their target dates.
- Jul 2026One Coordination Failure, on Two Clocks
Data center power stalls because the developer waits for a signed buyer, the buyer waits for a proven plant, and regulators wait to see which projects are real. Someone has to commit first, and if nobody is paid to, the risk lands on someone later.
- Jun 2026The Real AI-Power Risk Sits Downstream of the Megawatts
AI racks have gone from about 40 kW to 120 kW in two hardware generations, with 1 MW racks targeted from 2027. The power supply stays useful, but the electrical and cooling equipment inside the building may need rebuilding every few years.
Questions, corrections or disagreement on any of this are welcome: kris@tafelpower.com